Market overview and industry significance of the Lightweight Torpedo Market
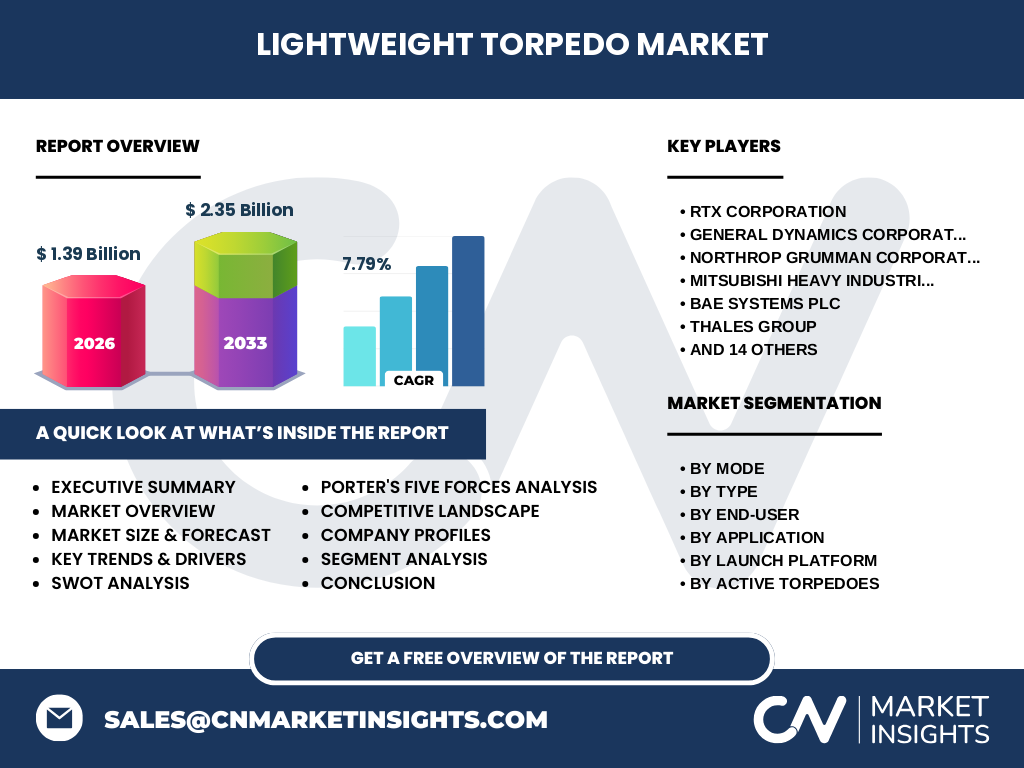
Our analysis indicates the Lightweight Torpedo Market represents a critical pillar of modern naval defense, valued at $1.39 Billion in 2026. This sector encompasses advanced underwater anti-submarine warfare munitions deployed primarily from aerial, surface, and sub-surface platforms. Industry significance is underscored by escalating geopolitical maritime disputes in the Indo-Pacific and Baltic regions, requiring highly agile ordnance capable of operating in shallow littorals.
Structural Growth Drivers and Market Restraints
The market is propelled by a 7.79% CAGR driven by naval fleet modernization initiatives and the proliferation of quiet diesel-electric submarines. Conversely, stringent environmental regulations regarding energetic materials like perchlorates and high-cost procurement hurdles act as primary restraints. Defense ministries increasingly demand modular propulsion systems to mitigate supply chain bottlenecks for critical rare-earth elements.
Emerging trends and growth patterns in the Lightweight Torpedo Market
The shift toward autonomous active torpedoes and advanced digital signal processing defines current sector trajectories. Navies are rapidly adopting broadband acoustic guidance to counter sophisticated acoustic countermeasures deployed by adversaries. This technical pivot favors prime contractors investing heavily in software-defined sonar architectures and AI-driven target discrimination algorithms.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions temporarily delayed composite casing deliveries and specialized microchip procurement for guidance sections. However, the post-COVID recovery trajectory has been exceptionally robust, fueled by supplemental defense appropriations from NATO member states. Budget reallocations prioritized naval deterrence, accelerating procurement backlogs across major defense shipyards globally.
Competitive Benchmarking and Strategic Dynamics
Industry concentration remains moderately high, dominated by established defense primes such as RTX Corporation, Leonardo S.p.A., and Naval Group. These major players maintain competitive moats through established defense ministry contracts and deep integration with anti-submarine warfare suites. Strategic dynamics involve cross-border joint ventures to transfer acoustic homing technology to allied navies.
Executive Summary of the Lightweight Torpedo Market
Our comprehensive research projects the Lightweight Torpedo Market market size to expand from $1.39 Billion in 2026 to $2.35 Billion by 2033. Accelerated by multi-domain littoral warfare demands and autonomous guidance integration, the sector offers high-margin opportunities for suppliers specializing in hybrid propulsion and acoustic counter-countermeasures.
Long-term Market Forecast from 2027 to 2033
Driven by sustained procurement cycles in the Asia-Pacific and European theaters, the market will scale steadily at a 7.79% CAGR over the 2027-2033 forecast period. The data suggests that procurement will peak between 2030 and 2032 as next-generation aerial launch platforms achieve full operational capability across allied naval aviation wings.
Comprehensive Segmentation Analysis
Market segmentation spans multiple operational vectors to address diverse naval mission profiles:
- By Mode: Electric Propulsion, Gas Propulsion, Hybrid Propulsion
- By Type: Active Torpedoes (Wire-Guided, Autonomous, Dual-Mode), Passive Torpedoes (Straight Running, Passive Sonar Homing, Quiet Operation Enhanced), Wake-Homing Torpedoes, Acoustic Torpedoes
- By End-User: Military, Naval Forces, Government Defense Agencies, Private Sector Security Companies
- By Application: Naval Defense, Anti-Submarine Warfare, Anti-Surface Warfare, Coastal Security Operations
- By Launch Platform: Submarine-Launchable, Ship-Launchable, Aerial Launch, Ground-Launchable
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily concentrated in regions facing heightened maritime security challenges. The Asia-Pacific region commands the dominant revenue share, driven by aggressive naval fleet expansions by India, Japan, and South Korea. Meanwhile, European demand is anchored by NATO interoperability mandates and increased maritime patrols in the North Sea.
In-depth Regional Review of High-Growth Zones
Our analysis highlights the Indo-Pacific as the primary growth engine, where nations contend with contested sea lanes and expanding submarine fleets. Domestic procurement initiatives by agencies like the Defence Research and Development Organisation and manufacturers like Bharat Dynamics Limited showcase a strong regional push for indigenous torpedo development alongside foreign acquisitions.
Company Profiles and Strategic Positioning
Key market participants deploy distinct strategies to capture market share. Lockheed Martin Corporation and Northrop Grumman Corporation leverage advanced aerospace manufacturing for lightweight air-launched frames, while Atlas Elektronik GmbH and Saab AB focus on specialized acoustic homing suites for shallow-water littoral operations. Asian innovators like LIG Nex1 Co Ltd and Mitsubishi Heavy Industries Ltd. anchor regional fleet requirements.
Porter's Five Forces Analysis of Competitive Pressures
The threat of new entrants is remarkably low due to prohibitive capital requirements, stringent military certification standards, and intellectual property moats surrounding acoustic guidance. Buyer power is concentrated among sovereign naval ministries, exerting downward price pressure, while supplier power is moderate, governed by specialized aerospace-grade titanium and explosive material vendors.
SWOT Analysis of the Lightweight Torpedo Industry
Strengths include high technological barriers to entry and mission-critical status in anti-submarine warfare. Weaknesses involve lengthy regulatory approval cycles and environmental liabilities associated with propellant testing. Opportunities lie in unmanned underwater vehicle integration, while threats stem from emerging disruptive asymmetric drone swarms.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw material extraction—specifically aluminum, titanium, and high-energy propellants—to specialized sub-component manufacturers producing acoustic transducers and guidance chips. Prime contractors assemble the final munitions, which are then distributed via defense logistics agencies to naval end-users stationed at strategic deep-water ports.
Strategic Investment Insights and High-Potential Areas
Investors should focus on software-defined acoustic processing and hybrid propulsion technologies, which address both range limitations and environmental concerns. Companies partnering with uncrewed maritime vehicle developers represent prime acquisition targets as navies seek to deploy lightweight torpedoes from autonomous platforms.
Conclusion and Key Takeaways for Market Stakeholders
The Lightwater Torpedo Market industry trends confirm robust expansion toward 2033, underpinned by geopolitical friction and technological modernization. Stakeholders must prioritize software adaptability and compliance with environmental regulations to secure long-term procurement contracts with major global naval forces.
Research Methodology and Baseline Estimation
Our baseline estimates are triangulated using a rigorous mix of primary stakeholder interviews with naval procurement officers, secondary macroeconomic defense budget allocations, and trade registry data from international defense export authorities. This multi-layered approach ensures high fidelity in our $2.35 Billion valuation forecast.
Scope of the Report and Analytical Parameters
This report covers global developments in lightweight underwater ordnance from 2026 through 2033. Analytical limitations include the confidential nature of classified military specifications and unlisted defense budgets in certain emerging economies, which are estimated using proxy macroeconomic indicators.
Recent Developments in the Lightweight Torpedo Market
Recent strategic moves feature significant contract awards for RTX Corporation and Thales Group regarding advanced counter-measure integration. Furthermore, technological partnerships between L3Harris Technologies Inc. and regional shipyards aim to field modular, easily upgradeable acoustic guidance packages for legacy ship-launchable platforms.